

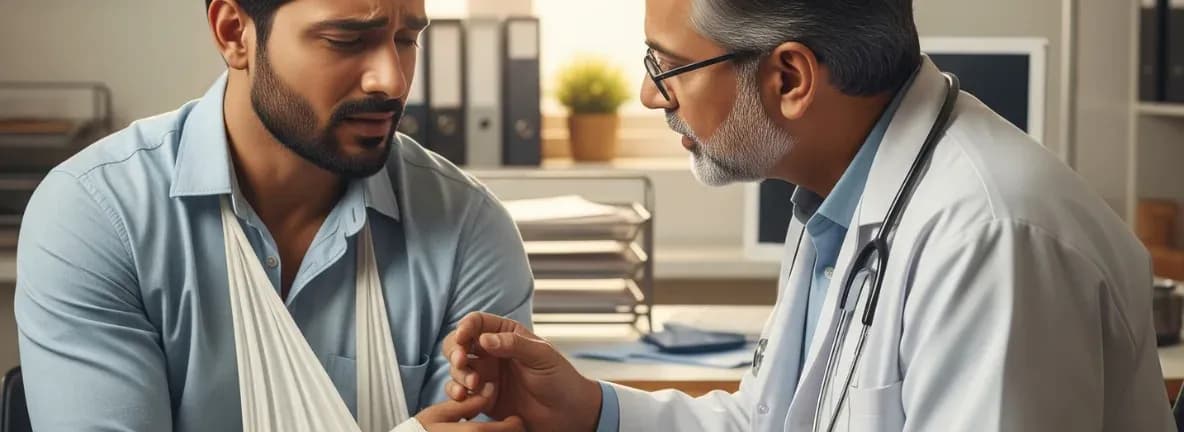
Does Health Insurance Cover Accidents and Injuries in India?
Pragya Shrivastava
Ashwin Chadha
Key Takeaways
- Health insurance generally covers eligible accident-related hospital expenses, subject to the sum insured, exclusions, deductibles, and policy limits.
- Personal accident insurance serves a different purpose, providing specified benefits for accidental death or disability. Medical expense cover may require additional protection.
- Check accident coverage start dates, hospital networks, disability benefits, and exclusions to understand gaps between your existing policies.
Introduction
Accidents can lead to emergency treatment, surgery, and hospitalisation without giving you time to plan expenses. If you are wondering whether health insurance covers accidents in India, the answer is generally yes.
Most health plans cover eligible medical expenses arising from accidental injuries. However, health insurance and personal accident insurance provide different types of financial protection.
What Are Accidental Injuries in Health Insurance?
Accidental injuries are bodily injuries caused by a sudden and unforeseen external event. Common examples include:
- Road accidents
- Slips and falls
- Burns
- Fractures
- Workplace accidents
- Cuts and physical injuries
- Sports-related injuries, where covered
Accidental injury coverage under health insurance in India generally focuses on medically necessary treatment rather than compensation for loss of income or disability.
Does Health Insurance Cover Accidental Injuries in India?
Yes, most health insurance policies cover eligible treatment required after an accident. This can include emergency hospitalisation, surgery, diagnostic tests, and medicines.
Unlike illnesses that may have an initial waiting period, accidental hospitalisation is commonly covered from the beginning of the policy. However, exclusions and policy conditions still apply. Jio Insurance Broking's current guidance also notes that most health plans provide accident-related hospitalisation coverage.
Therefore, accidental hospitalisation covered under health insurance depends on the treatment being medically necessary and admissible under your policy.
What Accident-Related Expenses Can Health Insurance Cover?
Coverage varies between plans, but an accident hospitalisation health insurance claim in India may include:
| Expense | Possible Coverage |
|---|---|
| Hospital room charges | Eligible room expenses within policy limits |
| Intensive Care Unit charges | Covered when medically required |
| Surgery | Eligible surgical treatment following the accident |
| Doctor's fees | Consultation and specialist charges |
| Diagnostic tests | X-rays, scans and other required investigations |
| Medicines | Prescribed medicines used during treatment |
| Ambulance | Covered up to applicable policy limits |
| Pre-hospitalisation | Eligible medical expenses before admission |
| Post-hospitalisation | Follow-up expenses within the specified period |
The final payable amount depends on the sum insured, deductibles, exclusions and applicable sub-limits.
Health Insurance vs Personal Accident Insurance: Key Differences
Understanding personal accident insurance vs health insurance in India is important because the two covers serve different purposes.
Personal Accident Insurance can therefore complement medical insurance when an accident causes demise, permanent disability, or loss of earning capacity.
Why Consider Personal Accident Insurance?
Health insurance can manage medical bills, but an accident can create financial consequences beyond hospital treatment.
- Accidental Demise and Disability Protection
Personal accident policies commonly provide a lump-sum benefit for accidental demise or specified permanent disability.
Some policies also provide benefits for permanent partial or temporary total disability, depending on their terms.
- Financial Protection for Your Family
A serious accident may affect your ability to earn. A defined benefit can provide financial support when disability interrupts income.
For accidental demise, the applicable benefit is generally paid to the nominee, subject to the policy conditions.
- Coverage for Hospitalisation Expenses
Some personal accident policies offer accident-related hospitalisation as an included benefit or optional extension.
Do not assume that every personal accident policy automatically reimburses medical expenses. Check the coverage schedule before purchase.
- Additional Protection During Travel
Many personal accident plans can provide protection beyond your home city and may offer broader geographical coverage.
However, territorial limits differ between insurers. Check whether international travel and specific activities are covered.
- Terrorism-Related Accident Coverage
Some personal accident policies may cover accidental injury caused by terrorism unless specifically excluded.
Coverage should be confirmed from the policy wording because this benefit is not identical across all insurers.
What to Check in Your Health Insurance Policy for Accident Coverage?
The answer to whether health insurance covers accidents in India also depends on the conditions attached to your chosen plan.
- Network Hospital Coverage
Check whether suitable hospitals near you are part of the insurer's Network Hospital list. A network hospital can help you request cashless treatment, subject to insurer authorisation.
- Sub-Limits on Accident-Related Treatment
Review room-rent limits, ambulance limits, co-payments and any procedure-specific restrictions. A sub-limit can reduce the amount payable even when the hospitalisation itself is covered.
- Waiting Periods
Many health policies exclude illnesses during an initial waiting period but make an exception for accidental hospitalisation. Always verify this condition in the policy wording rather than assuming every product follows the same structure.
Accident-Related Exclusions
Claims may be affected where injuries arise from excluded circumstances, depending on the policy.
Examples may include:
Intentional self-injury
Criminal activity
Substance-related exclusions
Certain hazardous sports
Treatments specifically excluded under the policy
- Add-On Covers for Additional Accident Protection
You may strengthen your protection through optional benefits where available.
Useful additions can include:
Personal accident cover
Hospital cash benefit
Critical illness benefits
Rehabilitation support
Temporary disability benefits
Additional ambulance benefits
Add-ons should be selected according to your occupation, travel frequency, financial dependants and existing insurance.
How Can Jio Insurance Broking Help You Choose Suitable Coverage?
Jio Insurance Broking is an insurance broker and does not underwrite insurance policies. It can help customers compare available health and personal accident insurance options across participating insurers. Customers can review premiums, coverage, exclusions and relevant benefits before choosing a policy.
For policies purchased through Jio Insurance Broking, it can also assist customers with the claim process. Claim acceptance, rejection and settlement remain the responsibility of the respective insurer.
How to Choose the Right Personal Accident Insurance?
Consider these factors before selecting personal accident cover:
Sum Insured: Choose protection that reflects your income and financial responsibilities.
Disability Benefits: Check permanent total, permanent partial and temporary disability provisions.
Occupation: Higher-risk occupations may require different coverage or underwriting.
Hospitalisation Benefits: Check whether medical costs after accidents are included.
Geographical Coverage: Review territorial restrictions if you travel frequently.
Exclusions: Understand activities and circumstances that are not covered.
Claim Requirements: Check documentation and reporting requirements beforehand.
The Health Insurance Claim process can also differ from a personal accident claim, so review both procedures separately.
Combine Medical and Accident Protection Carefully
Health insurance can cover eligible hospital expenses caused by accidents, but its main purpose is paying medical costs. Personal accident insurance addresses a different risk by providing financial benefits for accidental demise or disability.
Review your medical cover, occupation, income and financial dependants before deciding how much additional accident protection you require. Comparing both types of cover can help reduce gaps between hospital expenses and longer-term financial consequences.
FAQs
Is personal accident cover mandatory if I have health insurance?
No, a standalone personal accident insurance policy is not mandatory simply because you have health insurance. However, Compulsory Personal Accident (CPA) cover applies to eligible owner-drivers under applicable motor insurance rules. This motor insurance requirement is separate from regular health insurance.
What are the disadvantages of health insurance in India?
Health insurance policies in India may have certain limitations, including waiting periods, exclusions, co-payments, deductibles, room rent restrictions, and sub-limits. Coverage also depends on the selected sum insured, policy conditions, and the insurer's approved claim requirements.
Is ₹15 lakh accident cover mandatory in India?
A minimum ₹15 lakh Compulsory Personal Accident (CPA) cover is prescribed for eligible owner-drivers under applicable motor insurance regulations in India. This requirement relates to motor insurance and is separate from general health insurance. An eligible owner-driver may be exempt from purchasing duplicate CPA cover in certain circumstances, such as having qualifying existing personal accident coverage, subject to applicable rules.
What is not covered in a health insurance policy?
Common health insurance exclusions may include non-medically necessary treatments, specified cosmetic procedures, intentional self-injury, and treatments specifically excluded under the policy. Other exclusions and limitations may apply depending on the insurer and selected plan, so always review the policy wording before purchasing.
Do I need personal accident cover if I have health insurance?
Personal accident cover can provide additional financial protection even if you already have health insurance. While health insurance primarily covers eligible medical expenses, personal accident insurance can provide financial benefits in case of accidental death or disability. Your requirement depends on your income, occupation, financial dependants, and existing insurance coverage.
Disclaimers
Insurance coverage, exclusions, waiting periods, benefits and claim conditions vary between insurers and individual policies. Read the policy wording and Customer Information Sheet before purchase. Compulsory Personal Accident requirements mentioned above relate specifically to applicable motor insurance rules for eligible owner-drivers and should not be treated as a general requirement to purchase standalone personal accident insurance.
About the authors


